Sold as-is, but with clean title
The lender conveys marketable title and typically clears municipal and junior liens before listing. You still buy the condition as-is — but you are not inheriting someone else's lien stack.
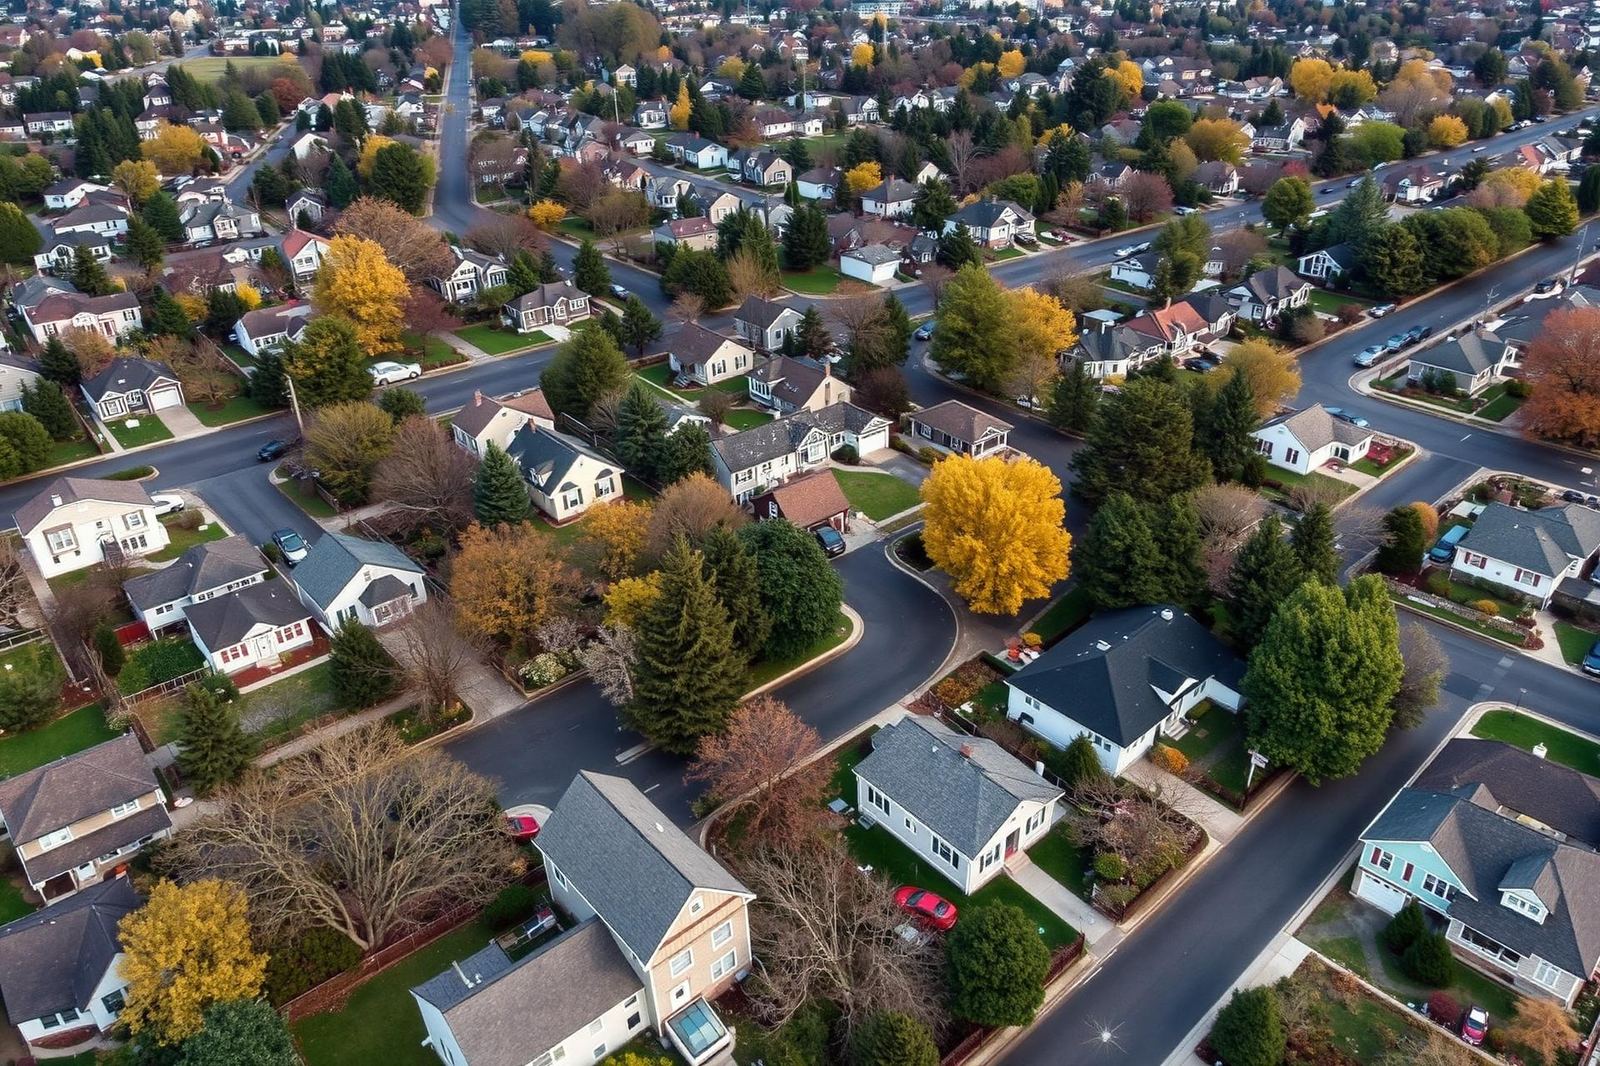
Bank owned (REO) homes are properties a lender took back after a foreclosure auction produced no third-party buyer. On Long Island they arrive on the OneKey® MLS through designated REO brokers — sold as-is, with clean title, title insurance available, and financing allowed. That combination is why most retail buyers who want a foreclosure actually end up buying bank owned.
New York is a judicial-foreclosure state. A Long Island lender must sue, win a Judgment of Foreclosure and Sale, and run a referee auction in Mineola (Nassau) or Riverhead (Suffolk) before it can take title. When nobody bids above the upset price — which is what usually happens — the lender takes the deed and the home becomes REO: Real Estate Owned.
From there an asset manager assigns the property to a local REO broker, orders a BPO (broker price opinion), completes evictions and cash-for-keys if needed, secures and winterizes the house, and lists it on the MLS. Typical lag between the auction and the MLS listing is 60–120 days.
For a buyer, bank owned is the safest way to buy distressed Long Island real estate: you get a title search, an inspection period in most cases, and the ability to use conventional, FHA 203(k), or renovation financing — none of which exist at the courthouse auction.
The lender conveys marketable title and typically clears municipal and junior liens before listing. You still buy the condition as-is — but you are not inheriting someone else's lien stack.
Unlike courthouse auctions, bank owned homes can be bought with conventional, FHA, VA, or FHA 203(k) renovation loans, provided the property meets the lender's habitability standards.
Most Long Island REO sellers allow an inspection period for information only. You cannot renegotiate on condition in most cases, but you can walk before your contingency expires.
Vacant homes on Long Island sit through winters. Budget for roof, boiler, plumbing freeze damage, mold remediation, and often a full kitchen and bath. Get quotes before you go firm.
REO contracts run on the seller's addendum, not the standard NY form. Per-diem penalties for late closings, no seller repairs, and short approval windows are normal — read them line by line.
Asset managers score offers on certainty and timeline as much as price. Proof of funds, a pre-underwritten approval, and a short due-diligence window routinely beat a higher, slower offer.
Every bank owned home in Nassau or Suffolk County passed through New York's judicial foreclosure system. The lender must first mail the borrower a 90-day pre-foreclosure notice under RPAPL 1304, then file a summons, complaint and lis pendens with the Nassau County Clerk in Mineola or the Suffolk County Clerk in Riverhead. That lis pendens is the public marker that a foreclosure has begun.
The case then moves through mandatory settlement conferences under CPLR 3408, where a homeowner can still negotiate a modification, a short sale, or a deed in lieu. If nothing resolves, the court issues a Judgment of Foreclosure and Sale and appoints a referee to run the auction.
At the auction the lender sets an upset price — the minimum it will accept, usually the judgment amount plus fees. Because upset prices on Long Island frequently exceed what third-party bidders will pay in cash, the lender bids its own credit, takes the referee's deed, and the property becomes REO: Real Estate Owned.
A referee's deed conveys whatever interest the foreclosed borrower had, and the foreclosure judgment extinguishes junior liens that were properly named in the action. Liens that survive — unpaid property taxes, water and sewer charges, village fees, and in some cases federal tax liens with redemption rights — are typically cleared by the bank before it lists the home, which is exactly why bank owned buyers get title insurance while courthouse bidders often cannot.
If the auction proceeds fall short of the judgment, the lender may pursue a deficiency judgment against the former owner under RPAPL 1371, but it must move within 90 days of the deed delivery. Most Long Island servicers waive deficiency in exchange for cooperation at the REO stage, which is one reason vacant, cash-for-keys transitions are common.
Nassau County bank owned inventory skews toward older capes, split-levels and colonials in Hempstead, Freeport, Roosevelt, Uniondale and Elmont, where taxes are high and carrying costs push distressed owners out fastest. Suffolk County inventory is broader: Brookhaven, Islip, Riverhead and Mastic Beach produce steady REO volume, while the East End produces a smaller number of much higher-value assets.
All of it reaches the public the same way — through the OneKey® MLS, syndicated by MLS GRID. Our search refreshes that feed every 30 minutes, so a bank owned home listed this morning by an asset manager in Texas shows up on this site the same day rather than a week later on an aggregator.
Because bank owned homes convey with insurable title, they are financeable. Conventional loans work when the home is habitable. When it is not — missing boiler, gutted kitchen, active leaks — an FHA 203(k) or Fannie Mae HomeStyle renovation loan finances the purchase and the repairs in one closing, which is the single most useful tool for buying Long Island REO that retail buyers walk away from.
Order the inspection immediately after contract, not at the end of your due-diligence window. REO addenda run on tight per-diem timelines and asset managers rarely extend. Bring an oil-tank sweep on older Suffolk properties, a mold assessment on anything that sat vacant through a winter, and a Certificate of Occupancy search with the town — unpermitted additions are the most common deal-killer on Long Island distressed sales.
Asset managers assign inventory to a small pool of designated brokers in each market. East End Luxury Ltd. holds those assignments across Nassau, Suffolk and the East End, which means we see occupancy checks, BPOs and list-price decisions before the listing goes live. For buyers on our alert list that translates into a head start measured in days, not hours.
If you are the homeowner rather than the buyer, the bank owned stage is the one you want to avoid. Before the referee's deed transfers you still control the outcome through a short sale, a modification, or a negotiated deed in lieu.
Institutional REO inventory and asset-manager disposition services.
Live OneKey® MLS distressed inventory, refreshed every 30 minutes.
How the stages of foreclosure differ for buyers.
RPAPL 1304, lis pendens, settlement conferences and auction.
What happens in Mineola and Riverhead before a home becomes REO.
Acquisition criteria, cash-buyer resources and deal flow.
Last reviewed May 27, 2026 by Kristopher J. Pilles, Licensed NY Real Estate Broker (CCIM, CDPE, MBA), East End Luxury Ltd. This page is general information about New York foreclosure and short-sale practice, not legal, tax, or financial advice. Consult a New York attorney, a CPA, or a HUD-approved housing counselor before acting on your own situation.
Confidential, no-obligation consultation with East End Luxury Ltd. — CCIM, CDPE, MBA.